Congratulations on taking the first step! This is your complete guide to buying a home in the Bay Area — how much cash you really need, the credit that qualifies you, and every step from budget to keys. We are Surbhi Gupta and Priyanka Chopra, California REALTORS® with eXp Realty of California, Inc., helping buyers across Fremont, Union City, Newark, Hayward, and Milpitas.
Ready to have us guide you in person? See how we help you buy → · Moving up? See how we help you move up →
How much cash do you actually need?
Most buyers need far less than they think. There are just three upfront costs:
- Down payment — as low as 3–5% for many buyers (you do not need 20%).
- Closing costs — roughly 2–3% of the purchase price (lender, title, escrow, and government fees).
- Cash reserves — about 2–3 months of mortgage payments lenders like to see in savings after closing.
Real example — a $1,000,000 home: about $90,000 total with 5% down, or about $240,000 with 20% down. Your exact number depends on your loan type and price point.
The credit score you actually need
Conventional — from 620FHA — from 580VA / USDA — lender-set
A higher score doesn’t just get you approved — it lowers your interest rate, which can save you tens of thousands over the life of the loan. Not there yet? Three fast wins:
- Pay every bill on time (payment history is the biggest factor).
- Get credit card balances under 30% of their limits.
- Don’t open or close accounts right before you apply.
Define your goals and budget
Start by getting clear on what you want and what you can comfortably afford. Think about location, commute, home type, and must-have features, and set a realistic monthly budget that accounts for the mortgage, property taxes, insurance, and any HOA dues.
Get pre-approved for a mortgage
A lender pre-approval tells you how much you can borrow and makes your offer credible to sellers. Do this before you start touring — it sets your real budget. We can connect you with trusted local lenders if you need one.
Search for the right home
With your budget and priorities set, we tour homes that fit. We help you compare neighborhoods, weigh trade-offs, and spot both the strengths and the potential issues in each property so you can move forward with confidence.
What’s a fair price for this home?
Before you offer, it helps to see whether a home is priced in line with the market. Use our quick fair-price tool to get a realistic range based on the details you enter:
A Bay Area Buyer's Guide
Am I paying a fair price?
A home's list price is an asking price — not proof of value. Here's exactly how to tell whether the number in front of you is fair, how to compete without overpaying, and the questions worth asking before you write an offer.
Prepared for you by Surbhi Gupta & Priyanka Chopra, REALTORS® · Bay Area Property Hub
Start here
List price is a starting point, not a verdict
Sellers (and their agents) choose a list price for many reasons — to test the market, to spark competition, or simply because they hope for it. A fair price is different: it's the number a willing buyer and a willing seller agree on, supported by what comparable homes have actually sold for recently.
The one thing to remember: value is set by recent sold prices of similar homes — not by the list price, not by what the sellers paid, and not by what they still owe.
The method
How a fair price is actually set
The same comparative process an appraiser and your agent use — a Comparative Market Analysis (CMA).
Pull recent comparable sales
Find homes that recently sold (not just listed) that are genuinely similar — comparable size, age, style, lot, and close by. Aim for sales within the last few months.
Adjust for the differences
No two homes are identical. Add or subtract value for square footage, condition, updates and finishes, garage and lot, layout, and features like a view or extra bedroom.
Factor in today's market
Supply and demand and interest rates move prices between the time a comp sold and today. A fast-moving market pushes the fair number up; a slower one softens it.
Land on a value range
The result isn't a single magic number — it's a defensible range. A fair offer sits inside that range for the home's real condition and the current market.
What moves the number
The four things that drive price
Location & lot
Commute and access, proximity to amenities, lot size and position, orientation, noise, and views. Two identical floor plans can differ in value by their setting alone.
Size & layout
Square footage, bedroom and bath count, and how usable the floor plan is. An open, functional layout is worth more than raw square footage alone.
Condition & updates
Move-in-ready vs. needing work — kitchens, baths, roof, systems, and cosmetics. Recent, quality updates command a premium; deferred maintenance discounts the price.
Market conditions
How much inventory is available, how fast homes are selling, and where interest rates sit. In a competitive market, fair value can land above the list price.
Read the room
Market signals worth checking
Before you anchor to a list price, look at what these tell you.
| Signal | What it tells you |
|---|---|
| Days on market | How long it's been for sale. Fresh listings draw competition; a long stint often hints the price is ahead of the market. |
| Price reductions | One or more cuts usually mean the original price didn't hold up — and that there may be room to negotiate. |
| List-to-sale ratio | How final sale prices compare to list prices in the area. Above 100% signals homes selling over asking; below 100% signals room below. |
| Months of inventory | Roughly how long it would take to sell all listings at the current pace. Low inventory favors sellers; higher favors buyers. |
Competing without overpaying
A strong offer is more than the price
In a competitive Bay Area market, paying above the list price can still be a fair price if the comps support it. And a well-structured offer can win without simply being the highest — sellers weigh certainty, not just dollars.
- Offer price & comps. Anchor your number to the value range, then position within it for the competition — not to a round number that "feels right."
- Contingencies. Inspection, appraisal, and loan contingencies protect you. Never waive protection you don't fully understand.
- Appraisal gap. If you offer over asking, know how you'd cover a shortfall if the appraisal comes in lower — and how much of that gap you're truly comfortable with.
- Earnest money & timelines. A solid deposit and reasonable close and possession terms signal a serious, low-risk buyer.
- Escalation clause. A way to automatically beat competing offers up to a firm cap you set — so you never pay more than you have to, or more than you've decided is fair.
Warning signs
Red flags a home may be overpriced
- It's priced well above recent comparable sales, with no clear reason (condition, upgrades, lot).
- It has sat on the market far longer than similar homes nearby.
- There have already been one or more price reductions.
- The price leans on future potential ("could add a bedroom") rather than what's there today.
- The listing compares itself to homes that are larger, newer, or more updated.
Quick reference
Your fair-price checklist
Run through this before you write an offer.
- I've seen recent sold comps — not just active listings — for similar homes nearby.
- I understand how this home differs from those comps, and roughly what those differences are worth.
- I know whether the market is pushing prices up, holding, or softening.
- I've checked days on market and any price history for this specific home.
- My offer sits inside a value range I can defend — not just a number that feels right.
- I know my walk-away price and how I'd handle an appraisal gap.
- My contingencies protect me, and I understand each one I'm keeping or waiving.
Before you offer
Questions to ask your agent
- What did truly comparable homes actually sell for in the last few months?
- How does this home's condition and location compare to those sales?
- What's the value range you'd support for this property — and why?
- Given the current market, where in that range should my offer sit to be competitive?
- What terms — beyond price — would make my offer stronger to this seller?
Client reviews
What our clients are saying


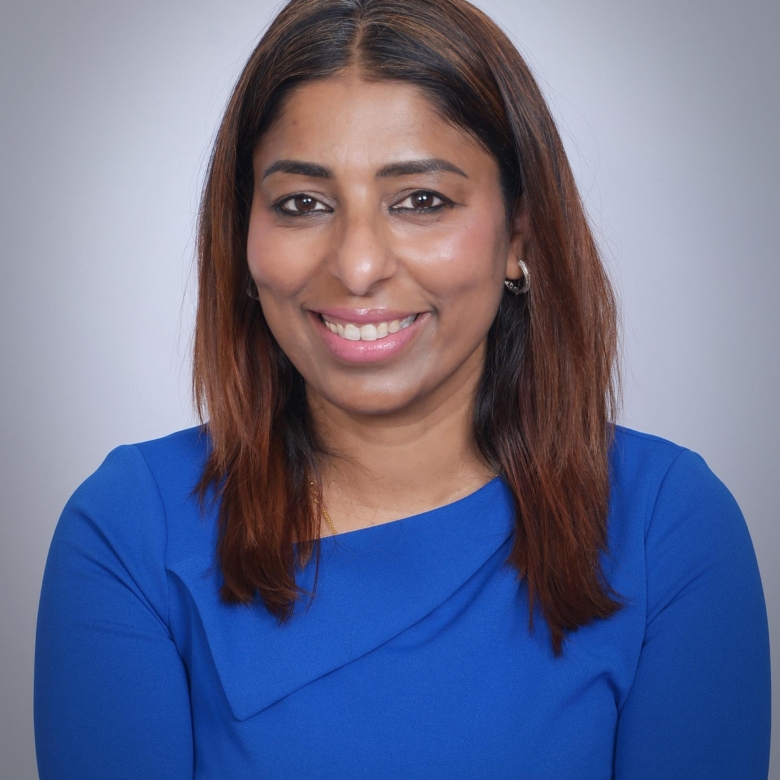
Your Bay Area agents
Surbhi Gupta & Priyanka Chopra, REALTORS®
We help buyers and sellers across Fremont and the greater Bay Area make confident, well-informed decisions — grounded in real data, clear guidance, and a genuine commitment to your best interests, from first search to closing day.
How we help
Let's find your fair number together
We'll pull the real comparable sales for any home you're considering, walk you through the value range, and help you write an offer that's both competitive and fair — so you buy with confidence, never guesswork. A buyer consultation is free, with no obligation.
This guide is provided for general educational purposes only. It is not an appraisal, a guarantee of value, or financial, tax, or investment advice, and it does not create an agency relationship. Market conditions and data change frequently. Please consult a licensed real estate, mortgage, legal, or tax professional about your specific situation before making a purchase decision.
Make a strong offer
When you find the right home, we prepare a competitive offer based on recent comparable sales and current conditions. Price is only part of it — terms, contingencies, and timing all shape how appealing your offer is to a seller.
Understand contingencies
Contingencies protect you during the transaction:
- An inspection contingency lets you evaluate the home’s condition
- An appraisal contingency addresses the home’s appraised value for your loan
- A loan contingency protects you while your financing is finalized
Inspections and disclosures
Once your offer is accepted, you review the seller disclosures and complete inspections. We help you read these carefully, understand what they mean, and decide how to respond — whether that is proceeding, requesting repairs, or renegotiating.
From accepted offer to closing
During escrow, your lender finalizes the loan, the appraisal is completed, and title and closing documents are prepared. From contract to keys is usually about 30–45 days. We keep the process organized and keep you informed at every step.
Costs to budget for
Beyond the down payment, plan for closing costs, inspection fees, homeowners insurance, property taxes, and any HOA dues on condos and townhomes. We’ll help you understand the full picture before you commit.
First-time buyer tips
- Get fully pre-approved before you start touring
- Learn what to expect at each stage so nothing feels like a surprise
- Review disclosures and inspection reports with a clear head
- Move at a pace that feels right for you, and never hesitate to ask questions
Ready for your personalized numbers?
This guide gives you the framework — your real budget, cash-to-close, and timeline are personal. Let’s map them out together on a quick, no-pressure call.
Home buyer FAQs
How do we start the home-buying process?
A good first step is a free consultation to talk through your goals, budget, and timeline, followed by getting pre-approved with a lender. From there we tour homes and build an offer strategy that fits you.
How much do I need for a down payment?
Down payment requirements vary by loan program, and some programs allow lower down payments. A lender can review your options, and we can connect you with trusted local lenders.
What is a contingency?
A contingency is a condition in your offer — such as an inspection, appraisal, or loan contingency — that gives you the ability to proceed, renegotiate, or withdraw based on what you learn.
How long does it take to buy a home?
Timelines vary, but many purchases close within about 30 to 45 days after an offer is accepted, depending on your financing and the terms of the contract.
Do I need a buyer’s agent?
A buyer’s agent represents your interests, helps you evaluate homes and offers, negotiates on your behalf, and manages the transaction to closing — typically paid through the transaction, so expert help costs you little upfront.
Which areas do you serve?
We help buyers in Fremont, Union City, Newark, Hayward, and Milpitas, along with the greater San Francisco Bay Area.
Explore areas and start your search
Ready to explore where you want to live? See our area guides for Fremont, Union City, Newark, Hayward, and Milpitas. Planning to sell as well? Read our home seller guide, learn about our buyer and seller services, or browse frequently asked questions.
Ready to buy in the Bay Area?
Let’s talk. Your consultation is free, friendly, and pressure-free — whether you’re just starting to explore or ready to make an offer.
— Surbhi Gupta & Priyanka Chopra, REALTORS® · CA DRE# 02314083 · CA DRE# 02252583 · eXp Realty of California, Inc.